Luxury Health Dashboard
Luxury's vital signs, on one page.
Data as of 23 Oct 2026 (Paris close). Updated 25 Oct 2026. Version 1.
Health score
Stable
Sales across the big groups are roughly flat and watch exports are growing again, but investors are pricing in something much worse. We read it as a sector that has stopped falling, not one that has started to recover.
- Sales. Median group growth, latest quarter: +1.0%stable
- Shares. Luxury basket vs STOXX Europe 600, YTD: −33.8 ptsweakening
- Watches. Swiss watch exports, 3 month average: +10.1%recovering
Method: each signal scores +1 (recovering), 0 (stable) or −1 (weakening). Sales: median group growth above 3% is +1, below 0% is −1. Shares: luxury basket more than 5 points ahead of the STOXX Europe 600 year to date is +1, more than 5 points behind is −1. Watches: 3 month average export growth above 3% is +1, below 0% is −1. Total of +1 or more is Recovering, −1 or less is Weakening, otherwise Stable.
Score over time
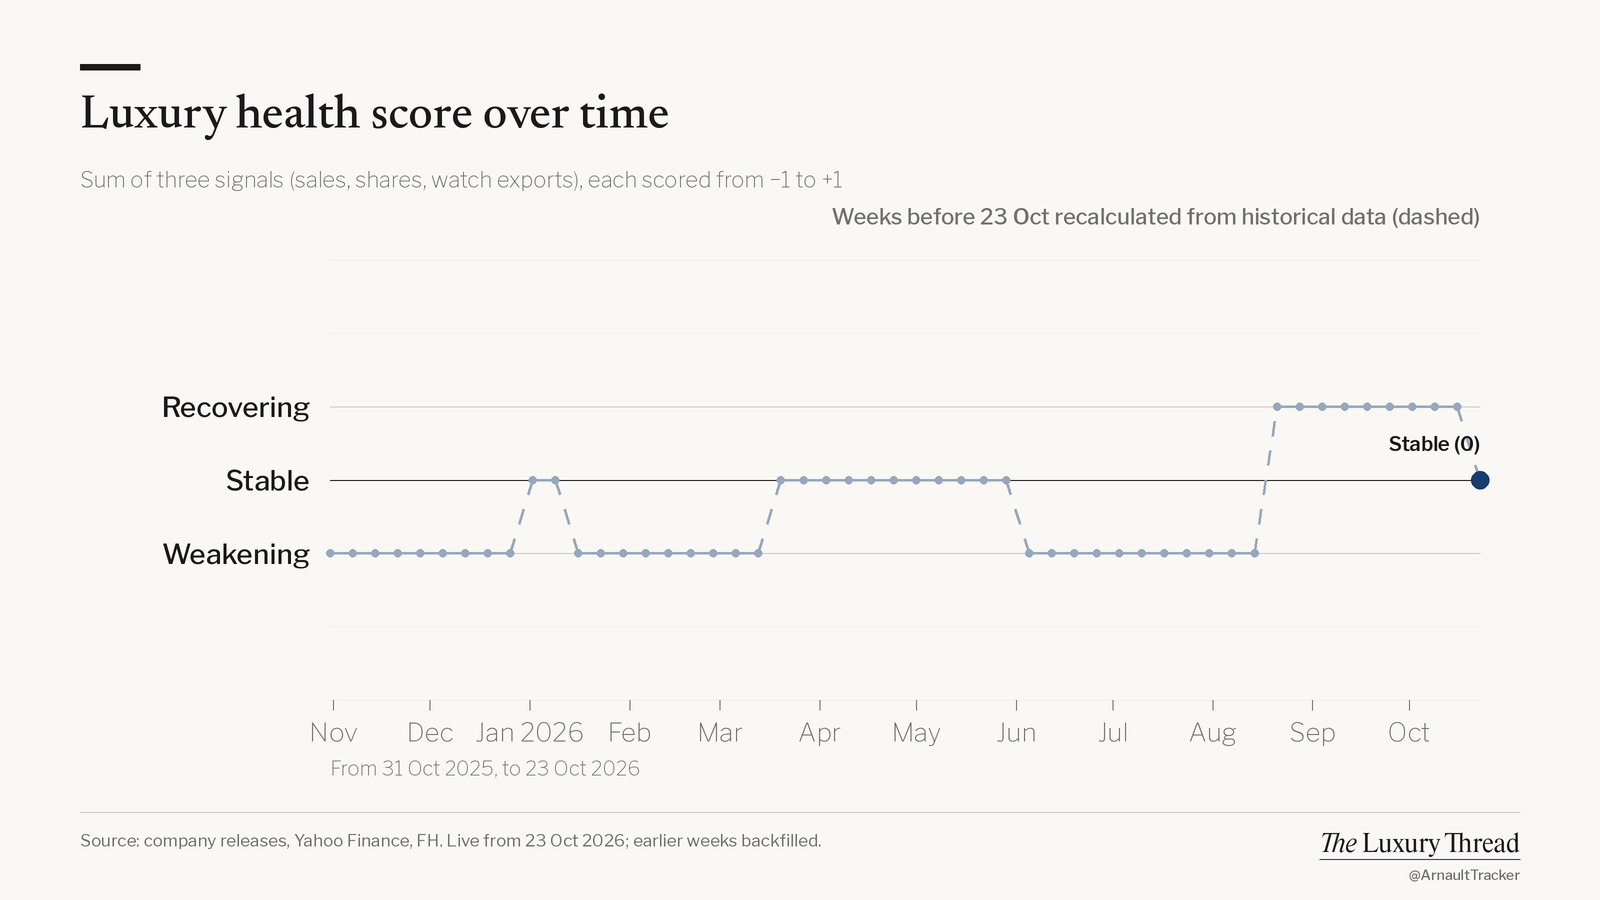
One point per data date, logged on every refresh. Fridays from 31 Oct 2025 to 16 Oct 2026 were recalculated with the same method, using only prices, results and FH export figures public on each date (dashed on the chart, flagged in the CSV). Share performance is measured year to date, so it resets each January; that is why the first two weeks of 2026 read Stable. Download CSV
What moved
- 23 Oct Kering −16.6% on the day after Gucci's Q3 (own stores −9%).
- 23 Oct Richemont −6.4% and Hermès −4.0% on the day.
- 22 Oct Hermès Q3 +4.3%, leather goods +10.8%; Kering Q3 −1%; Prada Q3 +1%.
- 21 Oct Moncler Q3 flat, Moncler brand −1%, Stone Island +5%.
- 20 Oct FH: Swiss watch exports +11.7% in September, China −14.2%.
1. Company results
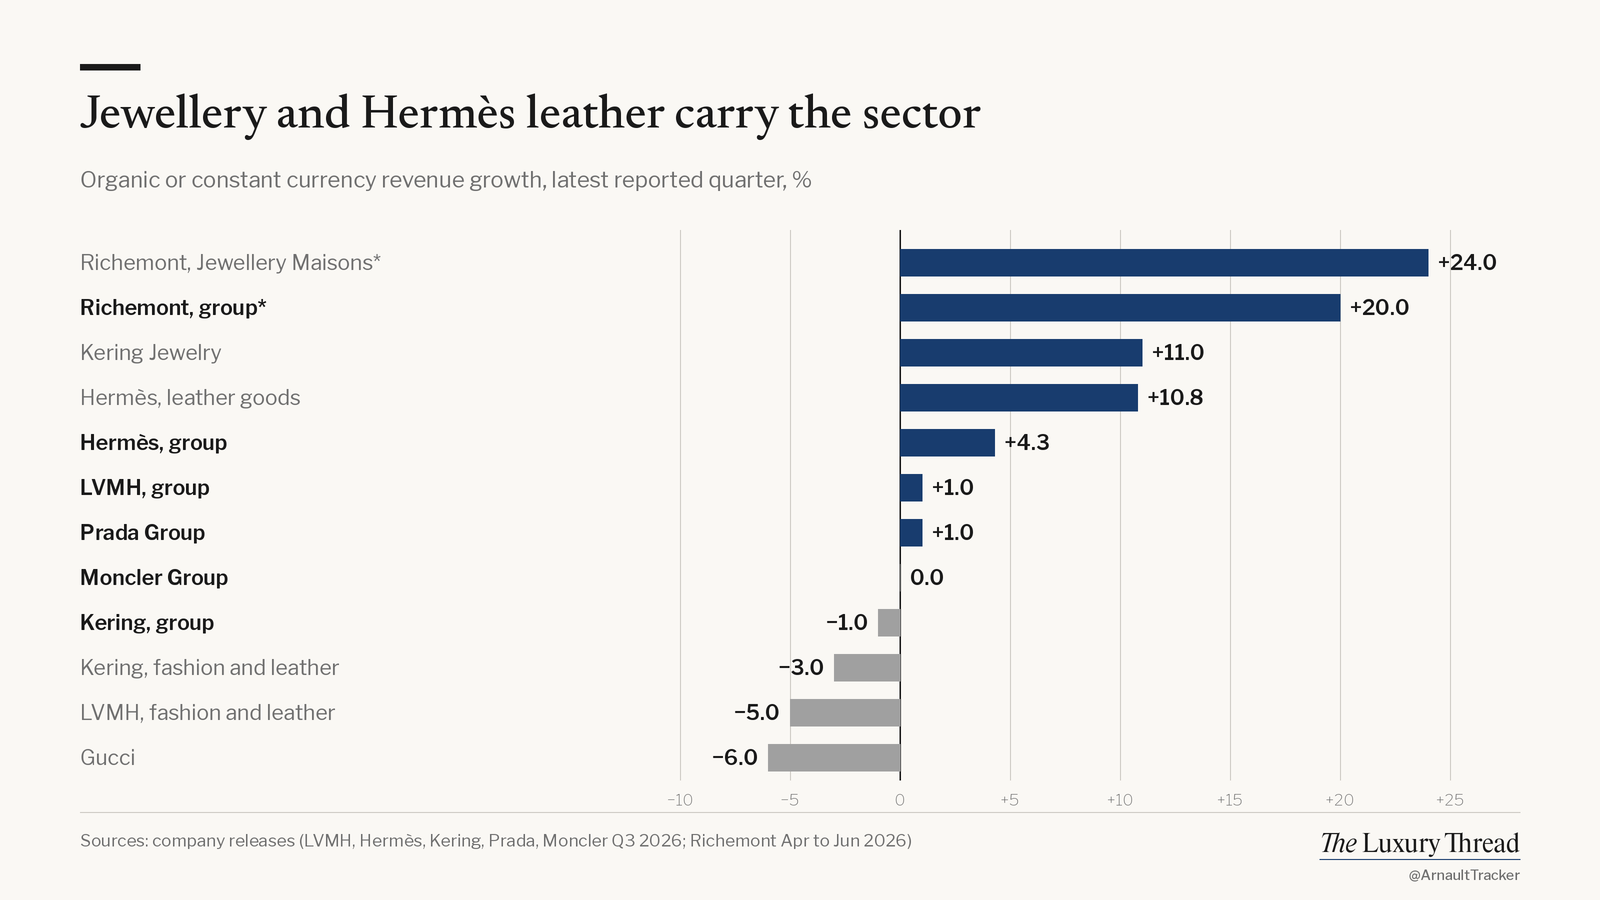
Jewellery and Hermès leather are growing. Fashion and leather at LVMH and Kering are shrinking, and Gucci is the weakest line on the board.
| Line | Growth | Our take |
|---|---|---|
| Richemont, Jewellery Maisons* | +24.0% | Cartier and Van Cleef are the best business in luxury right now. |
| Richemont, group* | +20.0% | Old quarter, but the strongest print in the group. Next update 13 Nov. |
| Kering Jewelry | +11.0% | Small, but growing double digits. |
| Hermès, leather goods | +10.8% | The waitlist still works. |
| Hermès, group | +4.3% | Slower, and it missed, but still well ahead of the pack. |
| LVMH, group | +1.0% | Sephora and jewellery are doing the lifting. |
| Prada Group | +1.0% | Prada holds; Miu Miu is cooling off a huge 2025. |
| Moncler Group | 0.0% | Tourist Europe hurt; Stone Island kept it flat. |
| Kering, group | −1.0% | Wholesale flatters a weak retail number. |
| Kering, fashion and leather | −3.0% | Saint Laurent and Bottega can't offset Gucci yet. |
| LVMH, fashion and leather | −5.0% | China is the drag, and it lands on Vuitton first. |
| Gucci | −6.0% | Own stores down 9%. The turnaround hasn't reached the tills. |
Organic or constant currency revenue growth, latest reported quarter (Q3 2026, July to September). *Richemont reports on a March year: Apr to Jun 2026, next update 13 Nov. Change vs previous quarter is not shown yet because not every house reports a comparable quarterly series. Sources: LVMH, Hermès Q3 release (finance.hermes.com), Kering, Richemont, Prada, Moncler 9M 2026 statement (monclergroup.com). Download CSV
2. Share prices
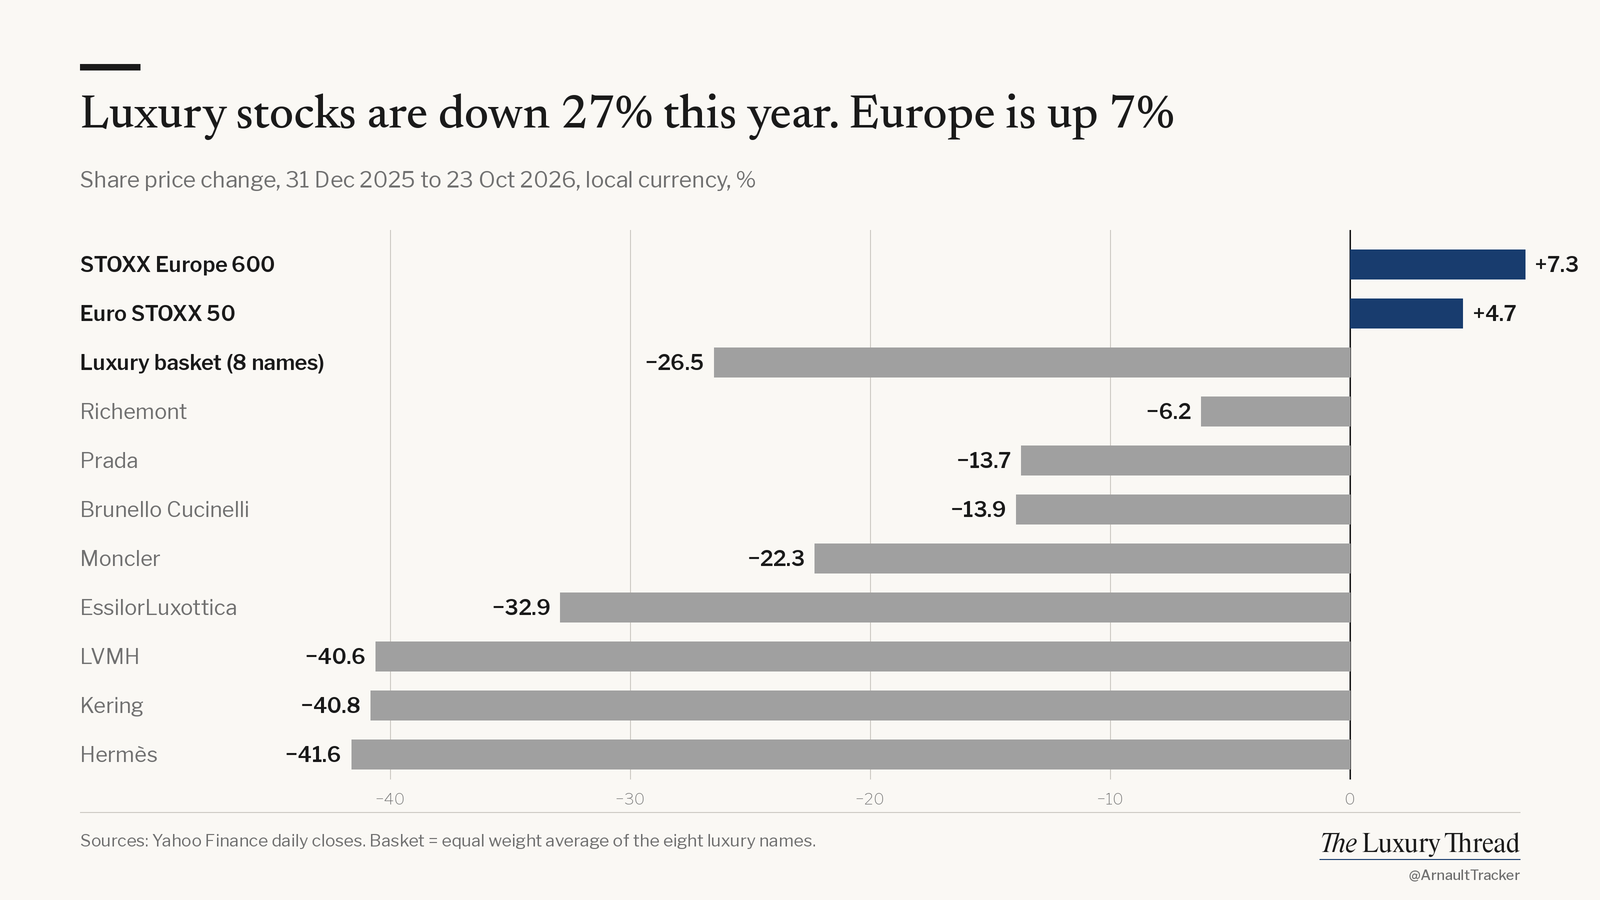
Europe's market is up this year. Luxury is down 26.5%, and the biggest names have fallen the most.
| Name | YTD | Our take |
|---|---|---|
| STOXX Europe 600 | +7.3% | The market is fine. This is a luxury problem. |
| Euro STOXX 50 | +4.7% | |
| Luxury basket (8 names) | −26.5% | Priced for a long slowdown. |
| Richemont | −6.2% | Jewellery is the place to hide. |
| Prada | −13.7% | Holding up better than most. |
| Brunello Cucinelli | −13.9% | Best grower in the sector, and the stock is still down. |
| Moncler | −22.3% | Tourist exposure is getting punished. |
| EssilorLuxottica | −32.9% | Bounced after Q3 but still a big loser. |
| LVMH | −40.6% | Fashion and leather weakness costs it everything. |
| Kering | −40.8% | Friday's 16.6% drop says investors have run out of patience. |
| Hermès | −41.6% | The premium multiple is unwinding even as sales grow. |
Share price change from the 31 Dec 2025 close to the 23 Oct 2026 close, local currency. Basket is the equal weight average of the eight names. Biggest moves on 23 Oct: Kering −16.6%, Richemont −6.4%, Hermès −4.0%. Source: Yahoo Finance daily closes. Download CSV
3. Swiss watch exports
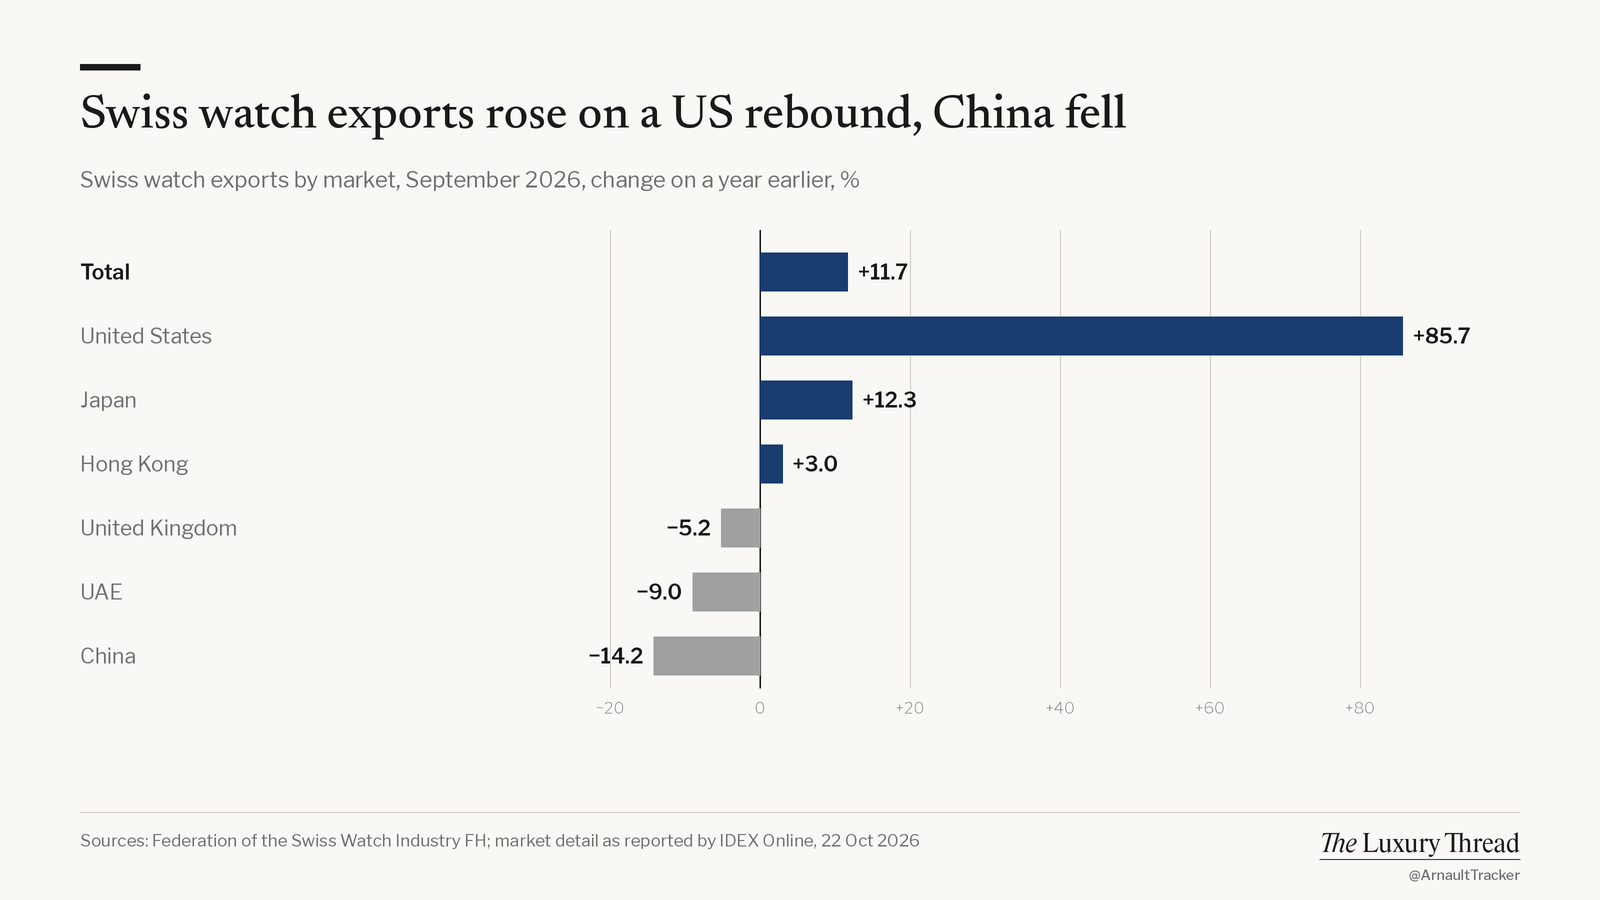
CHF 2,225.9m in September, up 11.7% on a year earlier. That's up from +9.1% in August and +9.6% in July. Strip out the US base effect and it looks a lot less exciting.
| Market | vs Sep 2025 | Our take |
|---|---|---|
| Total | +11.7% | Fourth month of growth in a row. |
| United States | +85.7% | Mostly a base effect after last year's tariff slump. |
| Japan | +12.3% | Steady local demand plus tourists. |
| Hong Kong | +3.0% | Barely positive. No sign of a real rebound. |
| United Kingdom | −5.2% | Still soft. |
| UAE | −9.0% | Gulf travel hasn't come back. |
| China | −14.2% | The weakest big market, and it matches what the brands say. |
Year to date: CHF 19.5bn, up 2.7%. Figures are exports, not sales to consumers. Sources: Federation of the Swiss Watch Industry FH; market detail as reported by IDEX Online; July and August via Keystone-SDA. Download CSV
Company scorecard
| # | House | Growth, latest quarter | Shares YTD | Margin | Valuation |
|---|---|---|---|---|---|
| 1 | Richemont | +20.0% Apr to Jun | −6.2% | not yet verified | not yet verified |
| 2 | Hermès | +4.3% Q3 | −41.6% | not yet verified | not yet verified |
| 3 | Prada | +1.0% Q3 | −13.7% | not yet verified | not yet verified |
| 4 | LVMH | +1.0% Q3 | −40.6% | not yet verified | not yet verified |
| 5 | Moncler | 0.0% Q3 | −22.3% | not yet verified | not yet verified |
| 6 | Kering | −1.0% Q3 | −40.8% | not yet verified | not yet verified |
Ranked on growth, then share performance. Margin and valuation columns stay hidden until we have figures checked against filings and a consistent price source; they arrive in version 2. Tap a house for its full profile, or browse all company profiles. For signals outside the score, see alternative indicators.
What's next
| Date | Event | What it could change |
|---|---|---|
| Tue 27 Oct | French Assemblée vote on the 2027 social security budget | A tax heavy outcome or a failed vote feeds France risk and pressure on French listed groups. |
| Tue 3 Nov | Assemblée vote on the revenue half of the 2027 budget | Any new levy on large companies or wealthy households would hit LVMH, Hermès and Kering sentiment. |
| Thu 12 Nov | Burberry interim results | First read on UK and aspirational demand after a soft summer. |
| Fri 13 Nov | Richemont half year results | Tells us if jewellery growth held up after the strong spring. |
| Tue 17 Nov | Assemblée vote on the full 2027 budget | Censure risk. A government fall would add to French market stress. |
| Mid Nov, date to confirm | China October retail sales | Gold and jewellery sales fell 9.6% in September. Another drop would confirm the China read. |
| Around 19 to 20 Nov, date to confirm | Swiss watch exports for October (FH) | Shows whether the US rebound is more than a base effect. |
| Fri 27 Nov | S&P review of France | A downgrade would weigh on French assets in general. |
| Late Jan 2027, date to confirm | LVMH full year 2026 results | The big one: does fashion and leather stop shrinking. |
| Thu 12 Feb 2027 | Hermès full year 2026 results | Leather goods versus everything else, again. |
Dates from official calendars and company announcements. Items marked "date to confirm" are expected, not announced.
Coming next: valuation (forward P/E and dividend yield against five year averages), demand by region, tourism and Paris footfall, and insider and buyback filings from the AMF.
Get the dashboard in your inbox every week.
A short weekly digest: the health score, what moved and what's coming. Plus the monthly report. Free, unsubscribe anytime.